CBAM Free Allocation Adjustment in 2026: SEFA, FAA and What the Declarant Surrenders

Published 21 July 2026 · Updated 18 October 2026 · 7 min read · Reviewed by Team GreenSutra

Night counting scene for the CBAM free allocation adjustment: a clerk weighs a full tray of amber tokens against a small stack before a steel plant

The CBAM free allocation adjustment, the FAA, is the deduction that mirrors EU ETS free allocation for imported goods. Commission Implementing Regulation (EU) 2025/2620, adopted 16 December 2025, sets out the method, and the rules have applied since 1 January 2026. For electricity the adjustment is zero. For other goods it cuts the number of CBAM certificates an authorised declarant must surrender, in step with the free allocation that EU producers of the same goods still receive. The quantity behind it is SEFA, the specific embedded free allocation: the free allocation embedded in one tonne of a good, expressed in tonnes of CO2e per tonne.

EU producers in CBAM sectors retain 97.5 percent of their free allocation in 2026, and the FAA mirrors that for imports. The declarant surrenders certificates for the embedded emissions minus the free allocation adjustment, and minus any carbon price deduction, never below zero. In 2026, 2.5 percent of the benchmark is no longer deducted. That figure is not 2.5 percent of the embedded emissions. The deduction shrinks each year, and from 2034 nothing is deducted for free allocation.

Key takeaways

  • The rule: Implementing Regulation (EU) 2025/2620 sets the methodology for the free allocation adjustment referred to in Article 31 of Regulation (EU) 2023/956.
  • The formula: the FAA for a good equals its SEFA for the year multiplied by the total mass of that good imported during the reporting year.
  • The effect in 2026: the declarant surrenders certificates for the embedded emissions minus the FAA, which still deducts 97.5 percent of the good’s benchmark.
  • The trajectory: the deduction falls to 95 percent of the benchmark in 2027, 51.5 percent in 2030 and 14 percent in 2033. From 2034 nothing is deducted for free allocation.
  • Where it lands: the FAA is included in the annual CBAM declaration, first due 30 September 2027, and certificate sales open 1 February 2027.

What the free allocation adjustment is, read from the rules

Regulation (EU) 2023/956 prices the embedded emissions of covered imports. Its Article 31 provides that the certificates to be surrendered are adjusted to reflect the free allocation still granted to EU installations producing the same goods. Implementing Regulation (EU) 2025/2620 supplies the method. It defines the free allocation adjustment as the adjustment to the number of CBAM certificates, and the specific embedded free allocation as the free allocation embedded in a good, per tonne, in tonnes of CO2e.

The logic runs parallel to the emissions side of the mechanism. Embedded emissions determine the gross obligation; the FAA then removes the share of that obligation which EU production of the same good does not pay either, because it still receives free allowances under the EU ETS. Both figures travel through the same document: the authorised CBAM declarant states the FAA in the annual CBAM declaration, and the certificates surrendered are the net of the two.

The regulation entered into force in December 2025 and applies from 1 January 2026, so the adjustment covers the first definitive-period year in full. There is no separate claim and no application: the adjustment is part of how the declaration is calculated.

The formula: SEFA times imported mass

The core of Implementing Regulation (EU) 2025/2620 is one line. For each good, the free allocation adjustment equals the specific embedded free allocation of that good for the year, multiplied by the total mass of the good imported during the reporting year. Everything else in the regulation explains how SEFA itself is derived.

The terms behind the CBAM free allocation adjustment
TermWhat it means
FAAFree allocation adjustment: the deduction from the CBAM certificates to be surrendered, per good, per year.
SEFASpecific embedded free allocation: free allocation embedded in one tonne of the good, in tonnes of CO2e per tonne.
CBAM benchmarksProduct benchmarks derived from the EU ETS free allocation benchmarks for the corresponding production routes.
CBAM factorThe phase-out factor from Article 10a(1a) of Directive 2003/87/EC: 97.5 percent in 2026, declining to zero as CBAM phases in.
Cross-sectoral correction factorThe EU ETS correction applied so the adjustment tracks what EU installations actually receive.

With actual production data, SEFA is calculated from the installation’s production process using the CBAM benchmarks, scaled by the CBAM factor and the cross-sectoral correction factor. Where the declaration rests on default values for the specific embedded emissions, the adjustment is calculated instead from predefined default CBAM benchmarks. These are matched to the same production routes and precursor assumptions as the emission defaults, so the two sides of the declaration stay consistent.
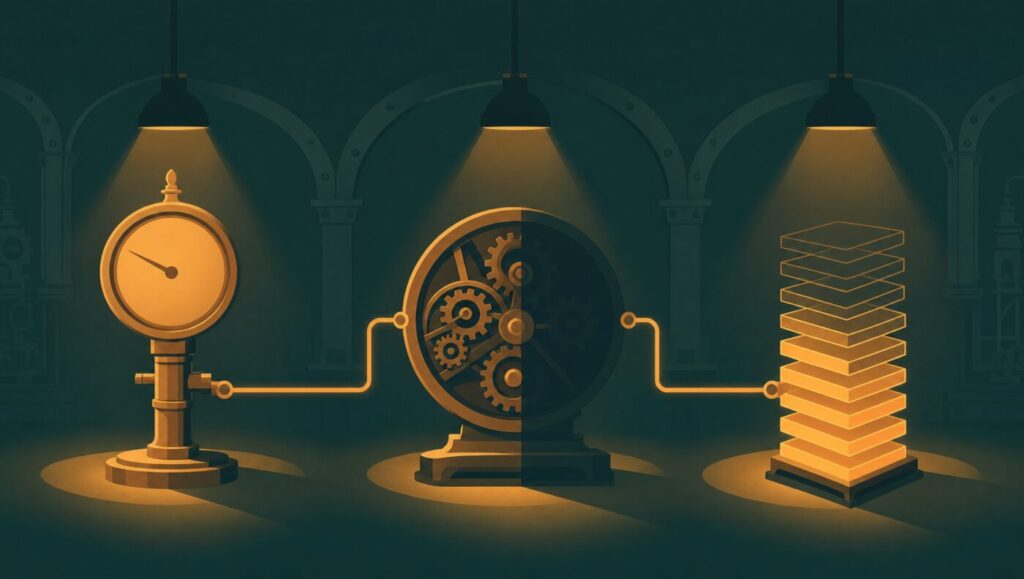
Three station chain for the CBAM free allocation adjustment: benchmark gauge, scaling gear wheel and a certificate stack fading at the top
CBAM benchmarks scaled by the CBAM factor and correction factor produce the allocation deducted from the certificates to surrender.

How the deduction shrinks, 2026 to 2034

Because the FAA mirrors EU free allocation, the deduction follows the free allocation phase-out schedule. The CBAM factor sets how much of the benchmark is still deducted:

The CBAM factor by year
YearShare of the benchmark still deducted (CBAM factor)
202697.5 percent
202795 percent
202890 percent
202977.5 percent
203051.5 percent
203139 percent
203226.5 percent
203314 percent
20340 percent

The certificate mechanics around the table: one CBAM certificate corresponds to one tonne of CO2e. Purchases open on the central platform on 1 February 2027. The price follows the EU ETS as a quarterly average of auction clearing prices in 2026 and a weekly average from 2027. The published figures so far are EUR 75.36 for Q1 2026, EUR 75.28 for Q2 and EUR 82.32 for Q3, published on 7 April, 6 July and 5 October 2026. The figure moves each quarter. From 2027, at the end of each quarter, the declarant must hold certificates for at least 50 percent of the emissions embedded in goods imported so far that year. These are worked out on default values without the mark-up, or on the prior year’s surrender, after the free allocation adjustment. The first annual declaration, covering 2026 imports, is due 30 September 2027.

Example: one tonne of Indian hot-rolled flat steel (CN 7208) imported in the third quarter of 2026 on default values. The default value of 4.280 tonnes of CO2e, with the 10 percent mark-up, gives 4.708. The FAA is 0.975 x 1.00 x 1.370 (CBAM factor x correction factor x default benchmark), or 1.336. The declarant surrenders 4.708 minus 1.336, or 3.372 certificates, about EUR 278 at the third-quarter 2026 price of EUR 82.32.

How fast the bill grows depends on how far a good’s emissions sit above its benchmark. On default values, Indian hot-rolled flat steel (CN 7208) needs 3.372 certificates a tonne in 2026 and about 4.86 in 2030, if the benchmark stays at its 2026 value. That is about 1.4 times, before any change in price. A plant whose emissions equal the benchmark starts far lower and rises much faster. Cost planning that starts from the 2026 figure alone understates the exposure the regulation has already scheduled.
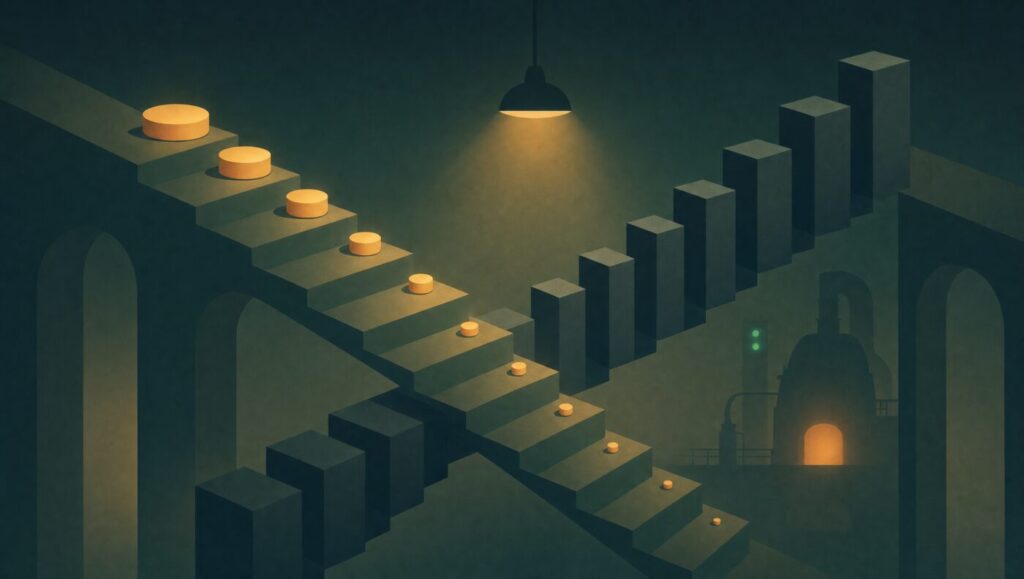
Two crossing staircases showing the CBAM free allocation deduction stepping down while the share of the benchmark no longer deducted steps up to 2034
The deduction steps down as the share of the benchmark no longer deducted rises from 2.5 percent in 2026 to 100 percent in 2034.

Two default systems, kept apart

The definitive regime now carries two separate default frameworks, and they pull in opposite directions. Implementing Regulation (EU) 2025/2621 supplies country of origin default values for the embedded emissions. Those defaults carry a mark up of 10 percent in 2026, 20 percent in 2027 and 30 percent from 2028, with a flat 1 percent for fertilisers. They inflate the gross obligation. Implementing Regulation (EU) 2025/2620 supplies default CBAM benchmarks for the free allocation adjustment; those feed the FAA, which reduces the certificates to surrender.

Read together, the two frameworks reward the same choice. Verified actual installation data lowers the emissions base by escaping the mark up, and the FAA then reduces what remains. Where verified installation data shows lower emissions than the marked-up default, the buyer needs fewer certificates. The rising mark up widens the gap against defaults until 2028. The default versus actual position for a specific product and volume can be estimated year by year in the CBAM cost calculator.

What the adjustment means for an exporter to the EU

The FAA belongs to the declaration of the authorised CBAM declarant, but its consequences reach the exporting installation. The certificates the declarant surrenders depend on the embedded emissions of the goods and the adjustment. Between two suppliers of the same product, the one whose verified emissions run lower delivers the smaller net certificate bill in each year the bill is above zero.

Preparation on the exporter side is the same work the rest of the regime rewards. It means a fixed and documented monitoring approach, source level records that reconcile, and a quantified default versus actual cost position per product line. GreenSutra works on that preparation side as a CBAM consultant: exposure assessment, embedded emissions calculation, supplier data collection and declaration ready reporting. Verification of the declared data belongs to the independent accredited verifier, and the two roles are deliberately separate under the EU rules.

The free allocation adjustment, answered

What is SEFA in CBAM?

SEFA is the specific embedded free allocation: the free allocation embedded in one tonne of a good, expressed in tonnes of CO2e per tonne, defined by Implementing Regulation (EU) 2025/2620. It mirrors the free allocation EU producers of the same good still receive under the EU ETS and feeds the free allocation adjustment that reduces the CBAM certificates the authorised CBAM declarant must surrender.

How is the CBAM free allocation adjustment calculated?

For each good, the free allocation adjustment equals the specific embedded free allocation of the good for the year multiplied by the total mass of the good imported during the reporting year. SEFA itself is derived from CBAM benchmarks based on the EU ETS free allocation benchmarks, scaled by the CBAM factor of Directive 2003/87/EC and the cross-sectoral correction factor. Where the declaration uses default values, predefined default CBAM benchmarks apply instead.

What share of emissions does the declarant surrender certificates for in 2026?

There is no fixed share. The authorised CBAM declarant surrenders certificates for the embedded emissions minus the free allocation adjustment, and minus any carbon price deduction, never below zero. EU producers in CBAM sectors retain 97.5 percent of their EU ETS free allocation in 2026, and the adjustment mirrors that allocation for imports. In 2026, 2.5 percent of the benchmark is no longer deducted. That figure is not 2.5 percent of the embedded emissions. The deduction shrinks each year, and from 2034 nothing is deducted for free allocation.

Does the free allocation adjustment make CBAM cost free?

No. The adjustment only mirrors the free allocation that EU production still receives, and that allocation is being withdrawn on a fixed schedule. How fast the bill grows depends on how far a good’s emissions sit above its benchmark. On default values, Indian hot-rolled flat steel (CN 7208) needs 3.372 certificates a tonne in 2026 and about 4.86 in 2030, if the benchmark stays at its 2026 value. That is about 1.4 times, before any change in price. A plant whose emissions equal the benchmark starts far lower and rises much faster.

The adjustment rewards prepared data. A CBAM readiness review fixes the monitoring approach, reconciles the records and quantifies the default versus actual position while the FAA is still at its largest. Start with the CBAM solutions page, map a specific export profile in a short CBAM discovery brief, or estimate exposure in the CBAM cost calculator.