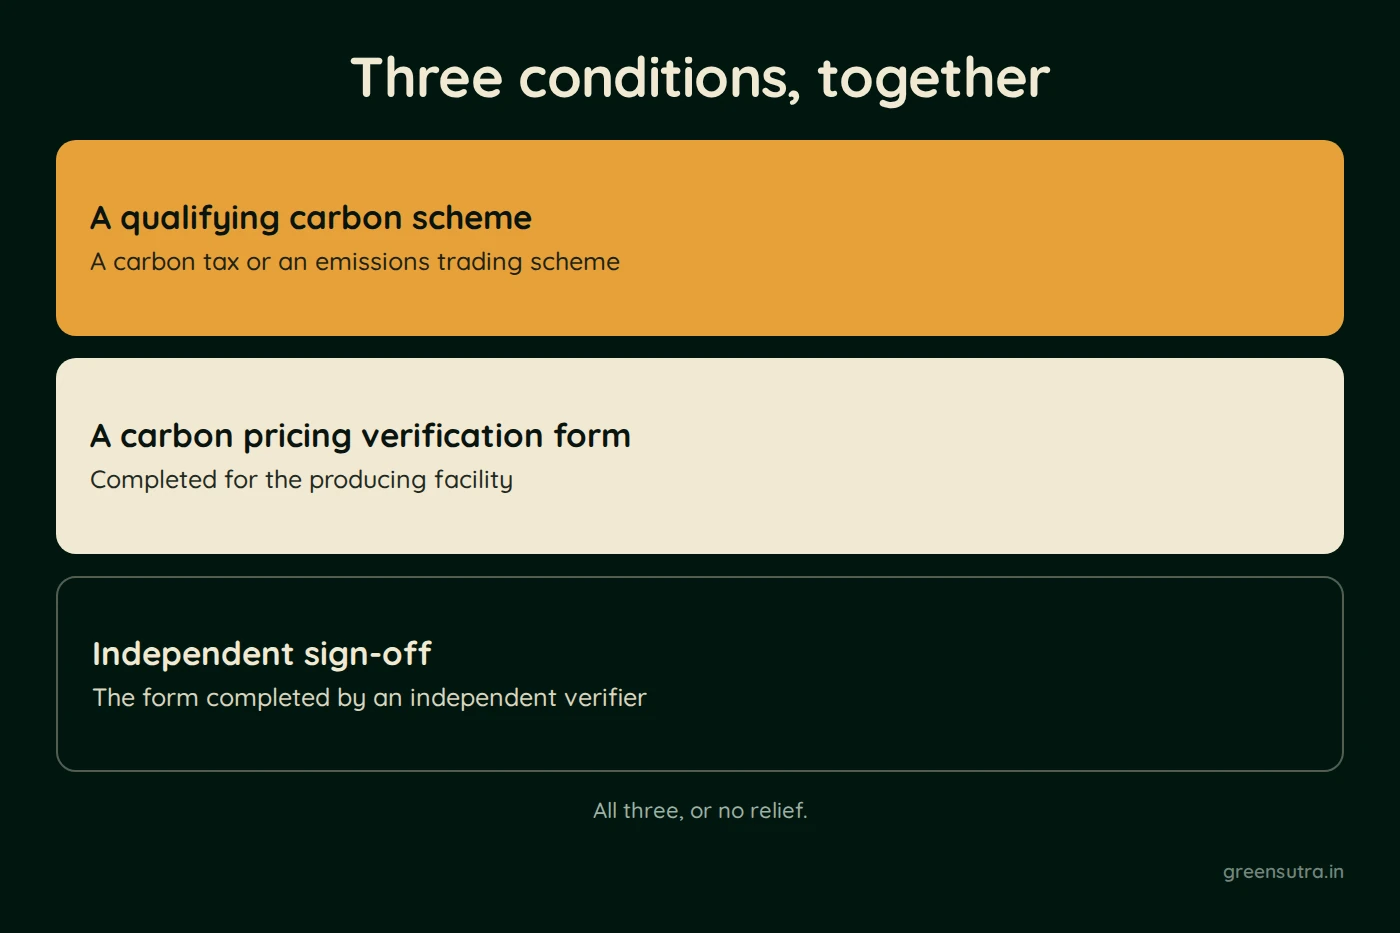
A UK importer can reduce the CBAM charge by a carbon price already paid overseas, but only where three conditions are met together: the price arises under a qualifying carbon scheme, the importer holds a carbon pricing verification form obtained from the producing installation or the supply chain, and an independent verifier meeting the required standards completed that form. All three are cumulative.
Carbon price relief is what stops the same tonne being priced twice, once in the country of production and again at the UK border. It is not automatic, and an importer that cannot evidence all three conditions pays the full charge.
The three conditions
| Condition | What it requires |
|---|---|
| Qualifying carbon scheme | The overseas price must arise under a carbon tax, an emissions trading scheme, or an imported goods scheme recognised as qualifying |
| Verification form | A completed carbon pricing verification form, obtained from the producing installation or the supply chain |
| Independent sign-off | The form must be completed by an independent verifier meeting certain required standards |
Missing any one of the three defeats the claim. The second and third conditions sit with the producing installation rather than the importer, which is the practical difficulty: the evidence has to come from a party in another jurisdiction that has no direct UK obligation of its own.
Why the scheme test is doing the heavy lifting
Whether a price counts turns on the design of the overseas scheme, not on whether a payment was made. The first condition, a qualifying overseas scheme, is the one to examine before assuming relief is available.
Record keeping
Records supporting a carbon price relief claim must be kept for six years. The period runs from the later of the date they were created and the end of the accounting period they relate to. The same applies to records for exempt goods and for weight measurement. A relief claimed but not evidenced is worse than a relief not claimed.
The verifier in the third condition is an independent third party. That role is performed by a verifier accredited to ISO/IEC 17029, ISO 14064-3, ISO 14065 and ISO 14066 and independent of the installation, the importer and the scheme’s jurisdiction.
Sources: GOV.UK CBAM collection, Finance Act 2026, Part 5
Establishing whether an overseas scheme qualifies, and getting the evidence out of the producing installation, is where relief claims succeed or fail. CBAM solutions covers supplier data collection for exporters, and the CBAM guide sets out the parallel EU treatment of a carbon price paid in a third country.