Indian steel exported to the EU without verified emissions data is assessed at India-specific default values published in Implementing Regulation (EU) 2025/2621: 2.53 tCO2e per tonne for pig iron, 4.28 for hot-rolled flat products and up to 6.50 for stainless flat products, each carrying a 10 percent mark-up in 2026 that rises to 30 percent from 2028.
How the default values are set
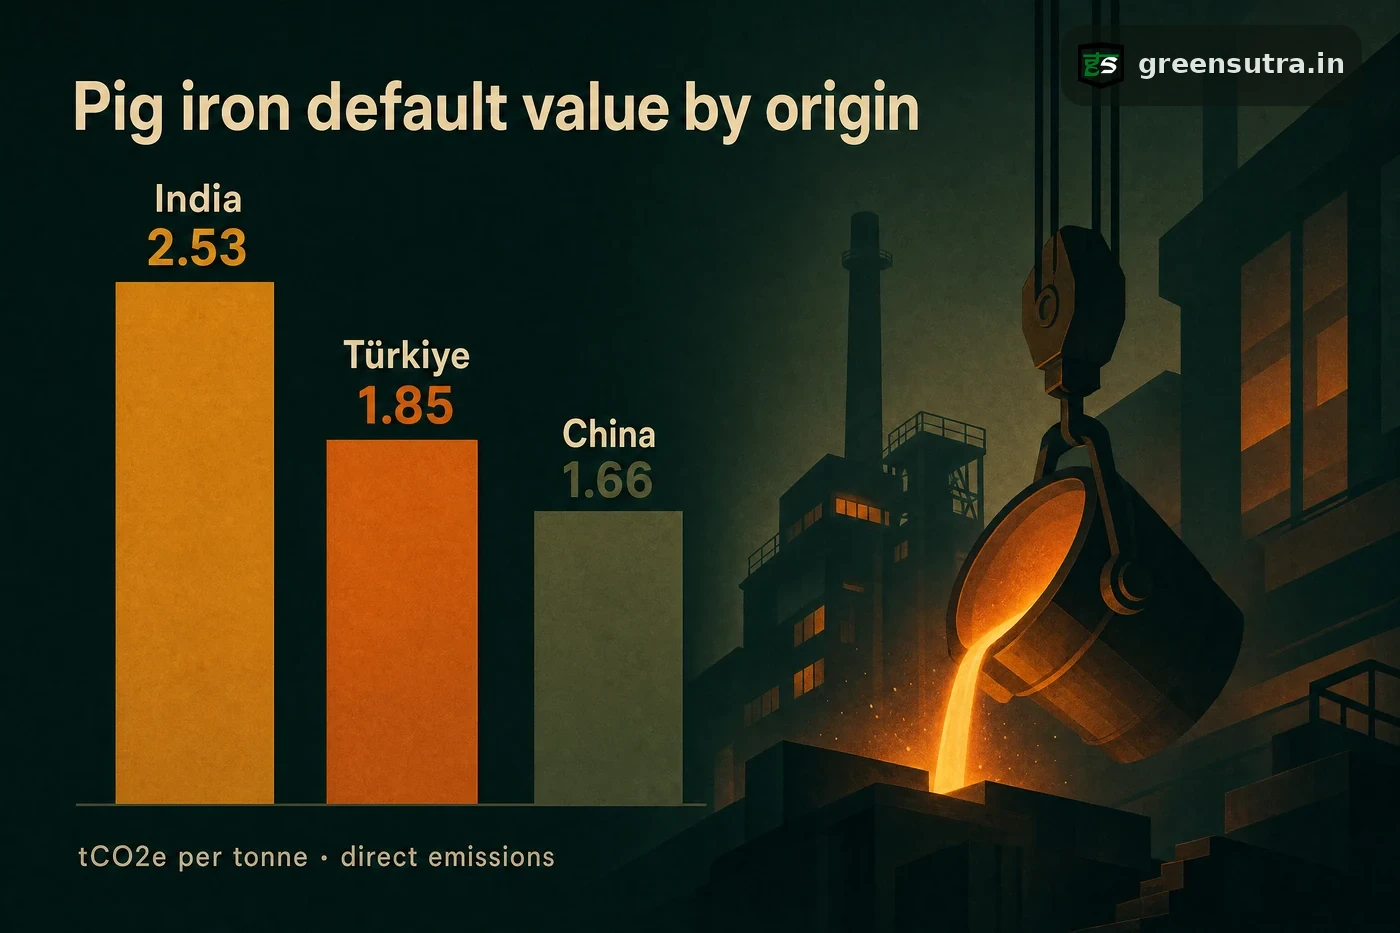
CBAM prices the carbon embedded in goods imported into the European Union. Where an importer declares iron or steel without verified installation data, the European Commission’s default values apply, and two rules shape the number. First, defaults are specific to the country of origin, so the India set differs from every other origin: pig iron carries 2.53 tCO2e per tonne for India against about 1.66 for China and 1.85 for Türkiye, with a 3.48 fallback for origins without a published pig iron value. Second, iron and steel is an Annex II good, so only direct emissions are priced; indirect, electricity related emissions are excluded. Each default then carries a regulatory mark-up of 10 percent in 2026, 20 percent in 2027 and 30 percent from 2028.
India default values for key steel products
| Product | Representative CN | Base default (tCO2e/t) | 2026 with mark-up |
|---|---|---|---|
| Pig iron | 7201 | 2.53 | 2.78 |
| Direct reduced iron (DRI) | 7203 | 4.20 | 4.62 |
| Hot-rolled flat products | 7208 | 4.28 | 4.71 |
| Bars and rods | 7213 · 7214 | 4.27 to 4.32 | 4.70 to 4.75 |
| Stainless flat products | 7219 | 6.49 to 6.50 | 7.14 to 7.15 |
Source: Implementing Regulation (EU) 2025/2621, Annex I. Direct emissions only.
What the defaults mean for an Indian exporter
On the default path the embedded emissions are taken at the marked up default. The declarant surrenders certificates for those emissions minus the free allocation adjustment, and minus any carbon price deduction, never below zero. The adjustment mirrors the free allocation EU producers of the same good still receive. On default values it is the good’s CBAM benchmark, times the CBAM factor for the year, times the cross-sectoral correction factor, times the mass imported. The CBAM factor is 97.5 percent in 2026 and falls each year; from 2034 nothing is deducted for free allocation. In 2026, 2.5 percent of the benchmark is no longer deducted. That figure is not 2.5 percent of the embedded emissions.
Example: a single line of 500 tonnes a year of hot-rolled flat steel (CN 7208) on the India default. For 2026 it needs 1,686 certificates, about EUR 138,792 if all of it were imported in the third quarter, at that quarter’s price of EUR 82.32. In 2034 the mark-up is 30 percent and nothing is deducted for free allocation. If the 4.28 default were unchanged, which the Commission must review by December 2027, the same line would need 2,782 certificates. That is about EUR 229,014 if the price were still EUR 82.32. Verified actual data can come in below the marked up default. If verified data came in at 2.2 tonnes of CO2e a tonne, roughly half the default, the 2034 bill would be 1,100 certificates, about EUR 90,552 at the same price.
Three steps follow for any exporter on the default path:
- Match every exported product to its CN code in Annex I of Regulation (EU) 2023/956.
- Compare the marked up India default against the installation’s actual production route; since 1 January 2026 either figure can go in the declaration, and only the actual one needs verification.
- Estimate the position year by year in the CBAM cost calculator, then take it to a CBAM consultant to prepare installation data for verification by an accredited verifier.
Sources: Implementing Regulation (EU) 2025/2621 · Regulation (EU) 2023/956