
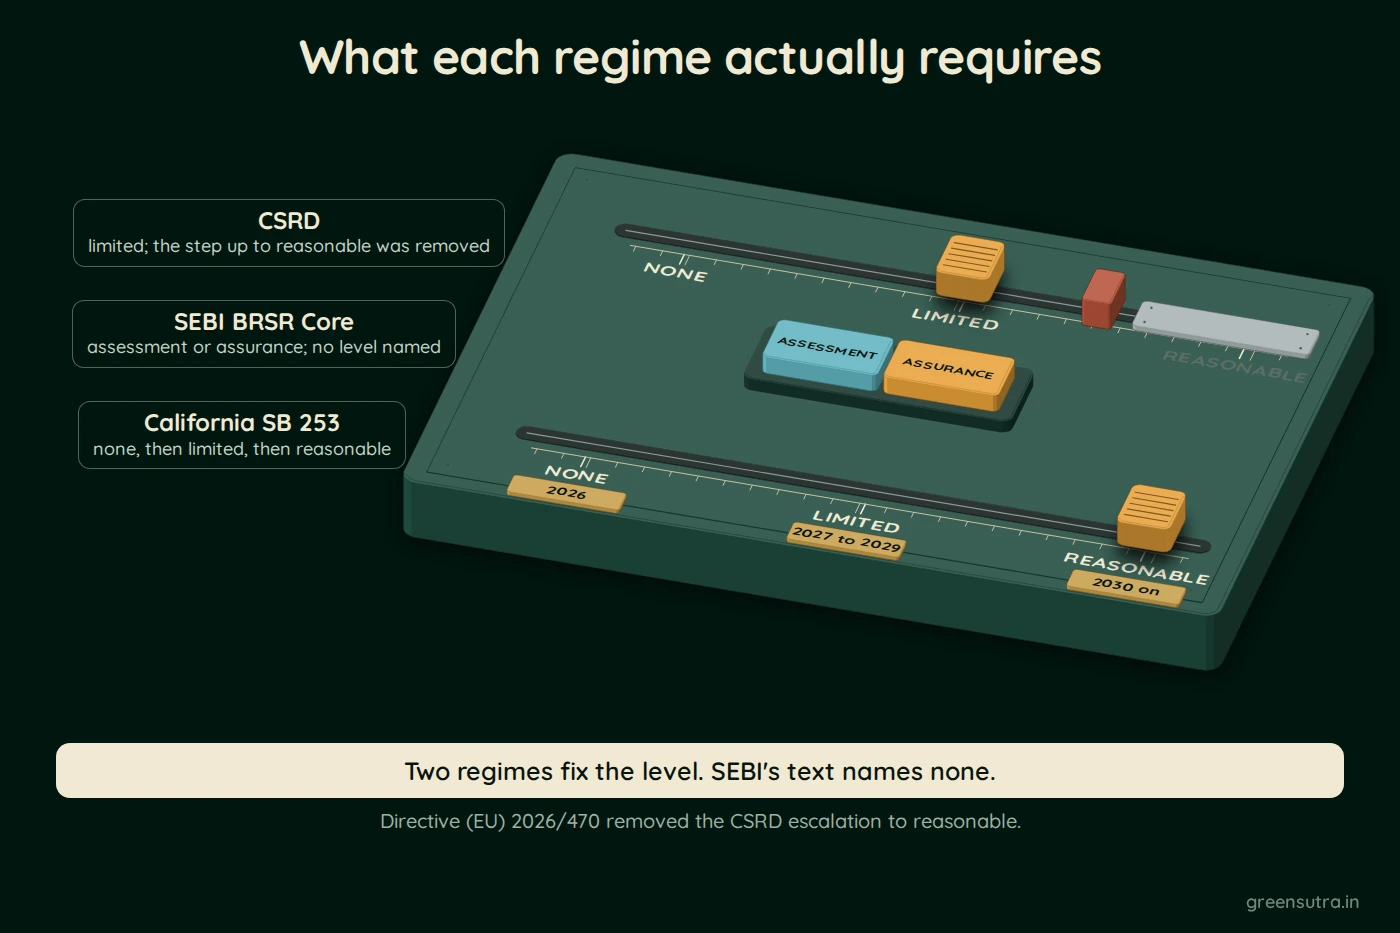
The three major regimes require different levels. CSRD retains limited assurance after the Omnibus, with the planned move to reasonable assurance removed. SEBI BRSR Core requires assessment or assurance, phased by market capitalisation rank, and its text names no level of assurance. California SB 253 requires no assurance in the first year, limited assurance from 2027 to 2029, and reasonable assurance from 2030.
Under CSRD and SB 253 the level is not a company’s choice. Each fixes it, and the levels produce different documents with different evidential weight. SEBI’s text for BRSR Core names no level, and Section A of the filing records which type of check was obtained.
What each framework requires
| Framework | Level required | Timing |
|---|---|---|
| CSRD, after the 2026 amending directive | Limited | Escalation to reasonable removed; limited assurance standard due no later than 1 July 2027 |
| SEBI BRSR Core | Assessment or assurance; no level named | Top 150 from FY 2023-24, top 250 from FY 2024-25, top 500 from FY 2025-26, top 1,000 from FY 2026-27 |
| California SB 253 | None in the first year, then limited, then reasonable | No assurance 2026, limited 2027 to 2029, reasonable from 2030 |
The two levels produce opposite conclusion forms
Reasonable assurance produces a positive form of conclusion: the practitioner states that the information is fairly presented. Limited assurance produces a negative form: the practitioner states that nothing has come to attention suggesting the information is materially misstated.
Inverting the two is the most common error in assurance copy, and it matters commercially because a reader expecting a positive opinion and receiving a negative-form conclusion has not received what was assumed. Reasonable assurance also involves substantially more work, including larger samples, evaluation of internal controls and extensive testing.
Where the Indian position differs
India asked its top 150 listed entities for reasonable assurance of BRSR Core from FY 2023-24, under SEBI’s July 2023 circular. A listed entity in the top 500 by market capitalisation already needed assessment or assurance of BRSR Core for FY 2025-26. An EU undertaking of comparable size continues on limited assurance with no scheduled escalation.
Since March 2025 an Indian entity may meet the requirement with either assurance or a third-party assessment under the Industry Standards Forum’s standards.
Sources: Directive (EU) 2026/470, SEBI BRSR Core framework circular, 12 July 2023
An entity reporting into more than one regime needs the highest applicable level built into its evidence base from the start. ESG solutions covers assurance readiness across frameworks, and the ESG guide sets out the disclosures each level is applied to.
Reviewed by Team GreenSutra on 15 November 2026.