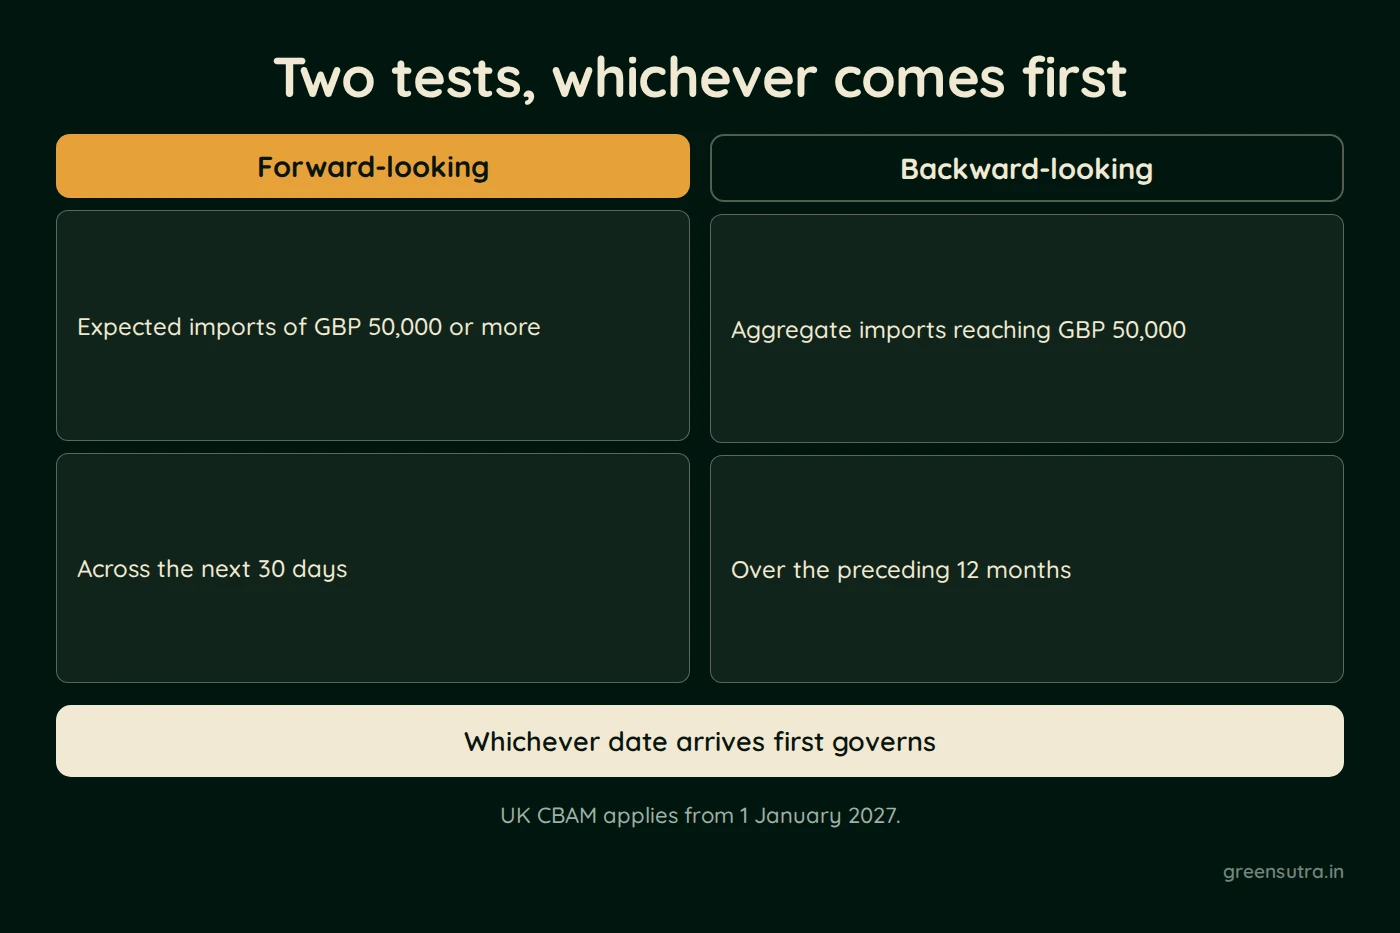
UK CBAM registration is triggered when imports of CBAM goods cross £50,000, tested two ways at once: expected imports of £50,000 or more within the next 30 days, or aggregate imports reaching £50,000 over the preceding 12 months. Whichever date arrives first governs. Registration opens on 1 January 2028, and importers liable in 2027 have until 31 January 2028 to register; later, 30 days from becoming liable.
UK CBAM applies to imports of CBAM goods from 1 January 2027. Unlike the EU threshold, which is a mass test, the UK threshold is a value test, and it is assessed continuously rather than once.
The two concurrent tests
| Test | What it asks | When it is assessed |
|---|---|---|
| Forward-looking | Whether the business expects to import CBAM goods valued at £50,000 or more | Across the next 30 days |
| Backward-looking | Whether the aggregate value of CBAM goods imported that count towards the threshold has reached or exceeded £50,000 | Over the preceding 12 months, assessed on the first day of each month |
Both run in parallel. An importer that never triggers the backward-looking test can still be caught by a single large forward order, and an importer with a steady low-value flow can cross the line on the monthly look-back without any single shipment being significant. The obligation bites on whichever date arrives first.
Why the UK and EU thresholds are not interchangeable
The EU de minimis is a cumulative annual net mass of 50 tonnes of CBAM goods per importer, introduced by Regulation (EU) 2025/2083. The UK threshold is £50,000 by value. The two cannot be converted into one another, and an importer into both markets has to track two entirely different measures on the same shipments. A consignment can sit below one threshold and above the other.
Dates that follow registration
Registration opens on 1 January 2028. The first accounting period is a single 12-month period running 1 January to 31 December 2027, with the first return and any payment due by 31 May 2028. As of 16 October 2026, HMRC sets returns and payments for the first two quarters of 2028 at 31 July and 29 September 2028. Later quarters fall due on the last working day of the second month after the period ends.
Sources: GOV.UK CBAM registration collection, Finance Act 2026, Part 5
Tracking two thresholds on one shipment flow is a data problem before it is a tax problem. CBAM solutions covers exposure mapping across both regimes, and the CBAM guide sets out the EU obligations that run alongside the UK ones.