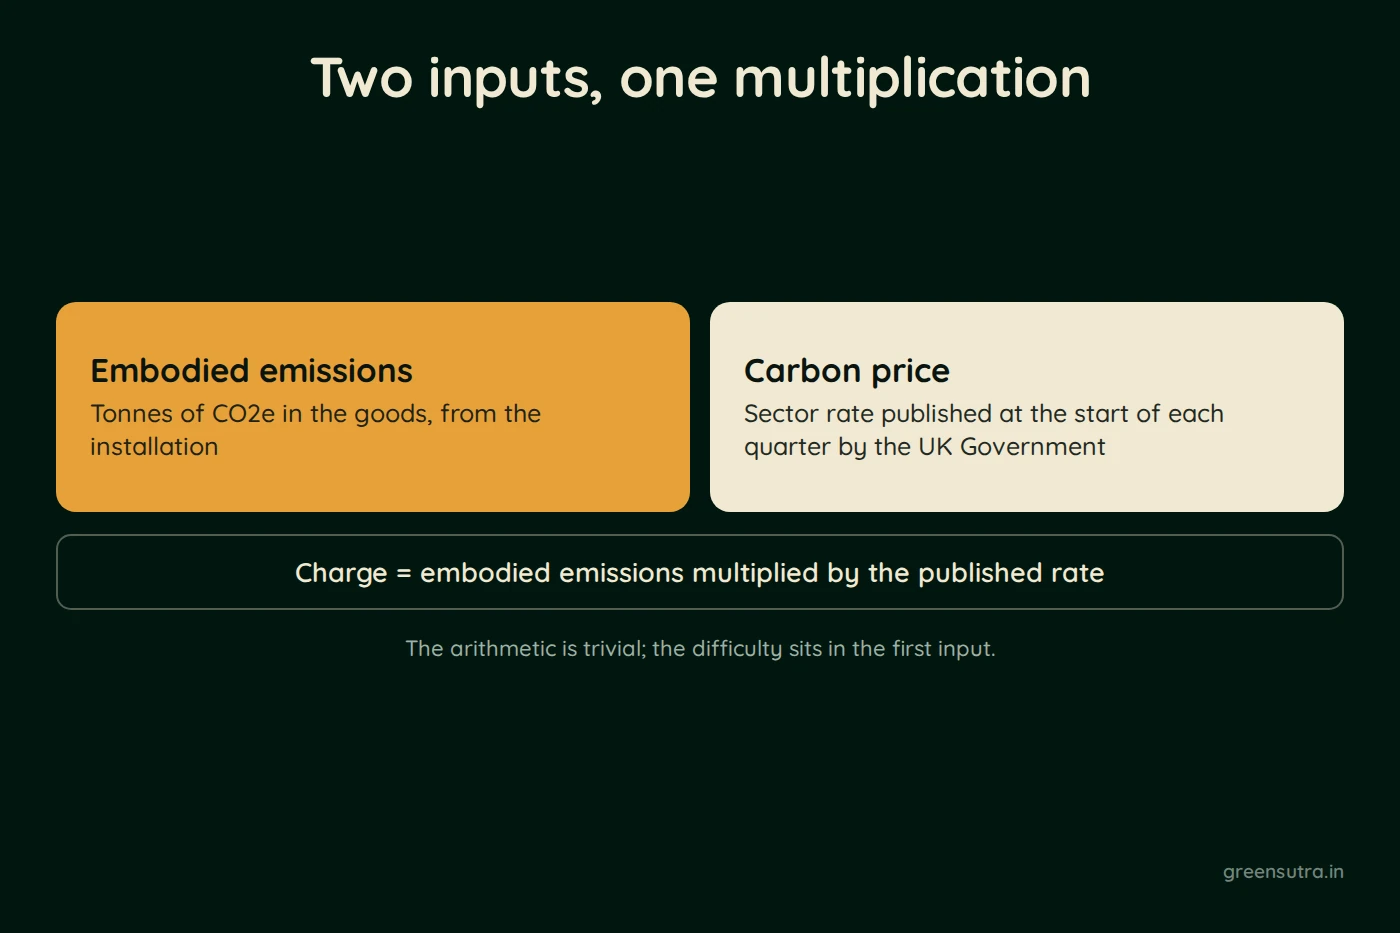
The UK CBAM charge is the quantity of embodied greenhouse gas emissions in the goods, in tonnes of CO2 equivalent, multiplied by the sector CBAM rate that the UK Government publishes at the start of each quarter. The rate is sector specific, and the one that applies is the rate in force in the quarter the goods were imported.
UK CBAM is a self-assessed tax rather than a certificate scheme, so there is nothing to buy in advance and nothing to surrender. The liability is computed on the return and paid with it.
The two inputs
| Input | What it is | Where it comes from |
|---|---|---|
| Embodied emissions | Greenhouse gas emissions embodied in the imported goods, expressed in tonnes of CO2 equivalent | The producing installation, supplied through the supply chain |
| Carbon price | The rate applicable to the relevant goods for the relevant quarter | Published by the UK Government at the start of each quarter, sector specific |
Multiplying the two gives the liability. The arithmetic is trivial; the difficulty sits entirely in the first input.
How the rate is set
The published rate is derived from the UK Emissions Trading Scheme auction price, adjusted for the free allocation share applying to that sector. That adjustment is what keeps an imported tonne broadly comparable with a domestically produced tonne, since UK producers in those sectors still receive free allocation. Because the rate moves each quarter, a liability cannot be quoted as a single constant figure. The mechanism should be stated, and any figure carried with the quarter it belongs to.
Direct emissions only at launch
Only direct emissions are in scope from 1 January 2027. Indirect emissions were excluded at launch and enter scope in 2029 at the earliest, confirmed by a UK policy paper published in November 2025. The stated reason was continued support for the Energy Intensive Industries Compensation Scheme. Sources published before November 2025 still describe indirect emissions from 2027 and are stale on that point. Direct emissions embodied in precursor goods stay in scope.
Precursor goods matter for steel. The HMRC policy summary of 16 October 2026 says the charge also covers the emissions embodied in relevant precursor goods used to make a complex CBAM good.
Sources: GOV.UK CBAM collection, Finance Act 2026, Part 5
Producing a defensible embodied emissions figure at installation level is the whole of the work. CBAM solutions covers embodied emissions calculation for exporters, and the CBAM guide sets out the equivalent EU methodology that most producing installations will already be building data for.