A US exporter of steel or aluminium into the European Union supplies installation-level embedded emissions data to its EU customer exactly as any other third-country producer does. Because there is no federal United States carbon price, the Article 9 deduction for a carbon price effectively paid in a third country is nil at federal level.
CBAM attaches to the goods and to the importer, not to the exporting country, so US origin confers no special position. What differs by country is only the Article 9 question of whether a carbon price was already paid.
What applies
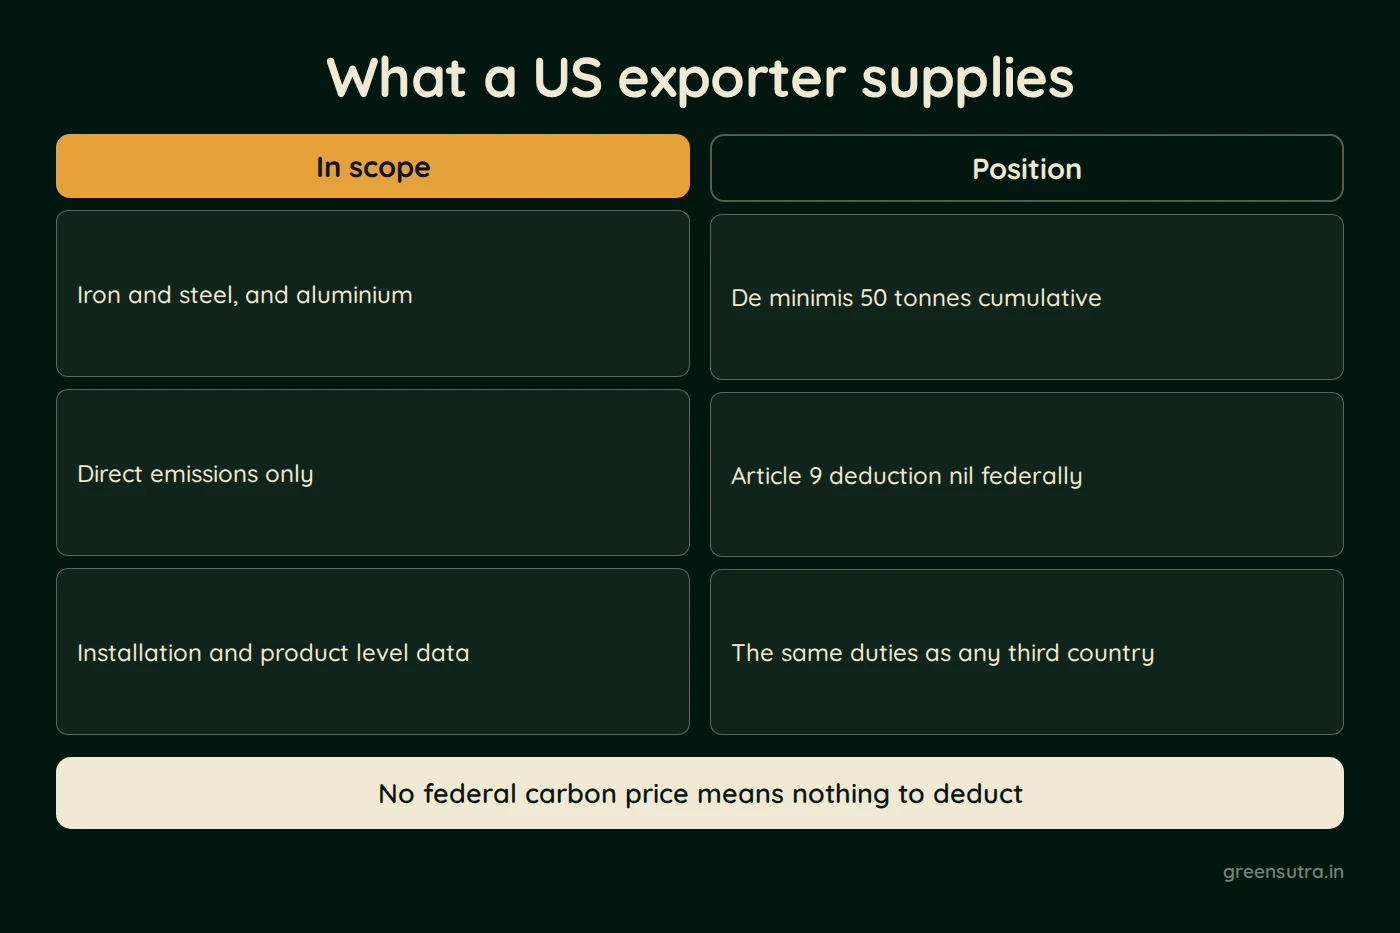
| Element | Position for a US exporter |
|---|---|
| Sectors | Iron and steel and aluminium are both Annex I sectors |
| Emissions priced | Direct emissions only, since both are Annex II goods |
| Data required | Installation-level, product-level embedded emissions on the Annex IV methodology |
| Threshold | The EU de minimis is 50 tonnes cumulative annual net mass per importer |
| Article 9 deduction | Nil at federal level, since there is no federal carbon price |
The federal position and the subnational one
The United States operates no federal carbon tax or federal emissions trading scheme, so at federal level there is nothing that could constitute a price effectively paid. California’s cap-and-trade programme is a subnational scheme. Article 9 has no step in which the EU recognises a scheme. A deduction needs a carbon price effectively paid on actual emissions, net of any rebate, with records certified by an independent person. With default values only yearly default carbon prices count, and the Commission had published none by 15 October 2026.
Where the obligation actually lands
Legal responsibility sits with the authorised CBAM declarant on the EU side. A US exporter carries no direct EU penalty exposure. What it carries is commercial exposure: a declarant unable to obtain supportable installation data falls back on country-of-origin default values, which attract an escalating mark-up, and that cost is priced back into the supply relationship.
For steel and aluminium that mark-up is 10 percent in 2026, 20 percent in 2027 and 30 percent from 2028, under Implementing Regulation (EU) 2025/2621.
Sources: Regulation (EU) 2023/956, European Commission, carbon price paid in third countries
The exporter’s practical task is producing installation data its EU customer can declare. CBAM solutions covers embedded emissions calculation for exporters, and the CBAM cost calculator sets out how the figures translate into exposure.