No. The India EU FTA gives no CBAM exemption. CBAM applies by product and country of origin regardless of trade agreements; the only origin carve-out is for countries in or linked to the EU Emissions Trading System, which does not include India. Verified emissions data, not the FTA, can reduce the cost where the plant’s actual emissions sit below the marked up default.
Why a trade agreement changes nothing under CBAM
As of 16 October 2026, the India EU FTA, concluded in January 2026, is not yet signed or in force and contains no CBAM exemption. Its Annex 14-A provides for a technical dialogue on CBAM, not an exemption. CBAM is a carbon pricing instrument created by Regulation (EU) 2023/956, not a customs duty, so tariff preferences negotiated between India and the EU operate in a separate legal lane. Liability turns on the product and the country of origin: iron and steel is one of the six covered product groups under Annex I, and the origin determines which default values apply when verified data is absent. The definitive regime has been live since 1 January 2026.
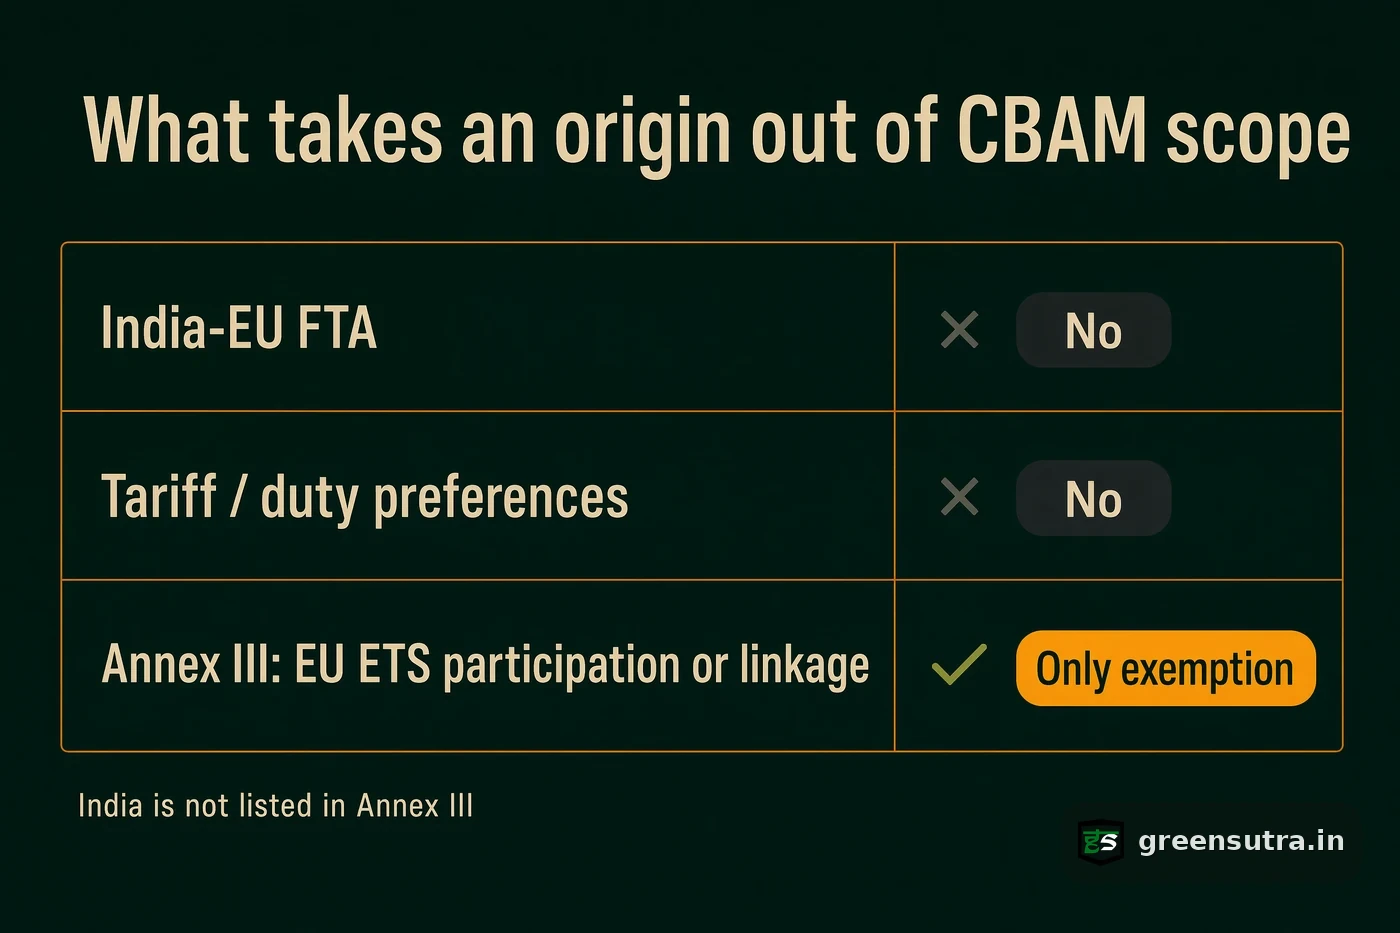
The only exemption by origin
Exactly one origin carve-out exists, and tariff deals do not create it. A separate exemption covers importers whose imported goods stay at or below 50 tonnes net mass in a calendar year. Annex III of Regulation (EU) 2023/956 places countries and territories that participate in or are linked to the EU Emissions Trading System outside CBAM scope. India has no such linkage, so Indian steel remains covered whatever the FTA settles on duties.
| Common assumption | What the regulation actually says |
|---|---|
| An FTA can waive CBAM | CBAM sits outside tariff schedules; a trade agreement does not amend Regulation (EU) 2023/956 |
| Duty preferences shrink the CBAM bill | The certificate obligation prices embedded emissions, not customs value or duty rates |
| An exemption for India can be negotiated later | Only Annex III listing, meaning EU ETS participation or linkage, takes an origin out of scope |
What actually lowers the bill
The levers that cut CBAM costs for Indian steel sit in emissions data, not in trade diplomacy.
- Verified installation data replaces the marked up India defaults, which carry a 10 percent mark-up in 2026, 20 percent in 2027 and 30 percent from 2028. The India figures are set out in the default values answer.
- Production route shapes the number that verified data reports: scrap-based EAF carries the lowest embedded emissions, gas-based DRI-EAF sits in the middle, and the BF-BOF route the highest. Duty preferences move none of these figures.
- Certificates are due for the embedded emissions minus the free allocation adjustment. That deduction shrinks each year: the CBAM factor is 97.5 percent in 2026, and from 2034 nothing is deducted for free allocation. In 2026, 2.5 percent of the benchmark is no longer deducted. That figure is not 2.5 percent of the embedded emissions. The advantage of verified data grows as the mark-up rises to 30 percent from 2028; the arithmetic is worked through in the exporter cost answer.
The CBAM guide maps the full compliance sequence, and the CBAM solutions service prepares embedded emissions calculations and installation data for verification by an accredited verifier.
Sources: Regulation (EU) 2023/956 · Implementing Regulation (EU) 2025/2621 · European Commission CBAM